
Articles


Construction employers face serious ACA employer mandate risk when seasonal hiring swings and variable-hour tracking gaps collide. Here's how to use look-back measurement periods and avoid COBRA liability.

Captives let employers own the insurance entity that covers their workforce, keeping underwriting profit and controlling cost trend. Here's when the structure makes sense and what size you need to get in.

A single group plan prices off a blended rate, which means low-cost geography employees subsidize high-cost ones. ICHRA's geographic class structure fixes that by calibrating defined contributions to local market pricing.

A MEC plan kills the ACA Part A penalty, but it leaves Part B exposure wide open. Here's what employers running MEC-only strategies for part-time or hourly populations actually owe if those employees buy subsidized coverage on the exchange.
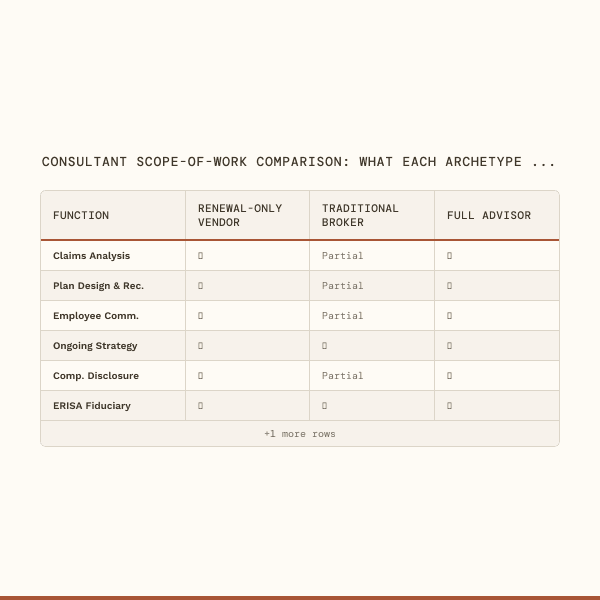
Most CEOs can't tell if their benefits consultant is working for them or for the carrier. Here are the 10 questions that expose the difference before your next renewal.

Mid-market employers lack the prescription volume to negotiate specialty drug prices directly, and the median list price of a new drug launched in 2024 topped $370,000. Collective models, stop-loss pooling, and PBM contract terms are the realistic levers available to CFOs and CEOs at 100-500 employee companies.

An ICHRA allowance does not add to an employee premium tax credit. It replaces it. That makes every ICHRA offer a head-to-head bid against the subsidy that employee would otherwise collect, and the 2026 subsidy rollback moved the crossover point down the income scale.

Reference-based pricing can reduce per-employee health spend by 28% or more, but the member experience, and whether those savings hold, comes down entirely to which vendor you pick and how they handle balance billing.

California's prescription drug mandates apply to fully-insured plans regulated by DMHC and CDI, where drug costs hit $14.9 billion in 2024. Self-funded ERISA plans are largely exempt, and that gap has real cost implications for California employers.

Most employers don't know if their health premiums are competitive because they've never seen a benchmark report. Here's what to ask for and what to do with the answer.

An 8-life Midwest group facing a 38% Anthem or UnitedHealthcare renewal has no negotiating power, because ACA rating rules removed the levers. Here are the three structural moves that are left, and the math behind each one.

A pre-open-enrollment audit checklist of 10 questions to ask your TPA in October, covering rate loading, portal readiness, MHPAEA compliance, ID card production, and enrollment controls.